You need money for a medical emergency, a car repair, or an unexpected expense. You aren't sure which type of loan is right for you. According to TransUnion data (Q1 2026), Americans hold $277 billion in personal loan debt across 26.4 million accounts. It’s a massive system. If you're wondering what types of loans are out there, navigating it without clear information in your own language can feel overwhelming.
According to the Federal Reserve (2025), 12% of Hispanic adults are unbanked, often because the financial system wasn't designed with our community in mind. Many of us grew up with informal savings circles (tandas), loans between family members, and the trust of a handshake. That isn't a weakness: it's real financial experience. Formal loans in the U.S. operate under different rules, and knowing what types of loans exist empowers you to make better decisions.
In this guide, you will learn about the different types of loans, their benefits, their risks, and which one works best for your situation.
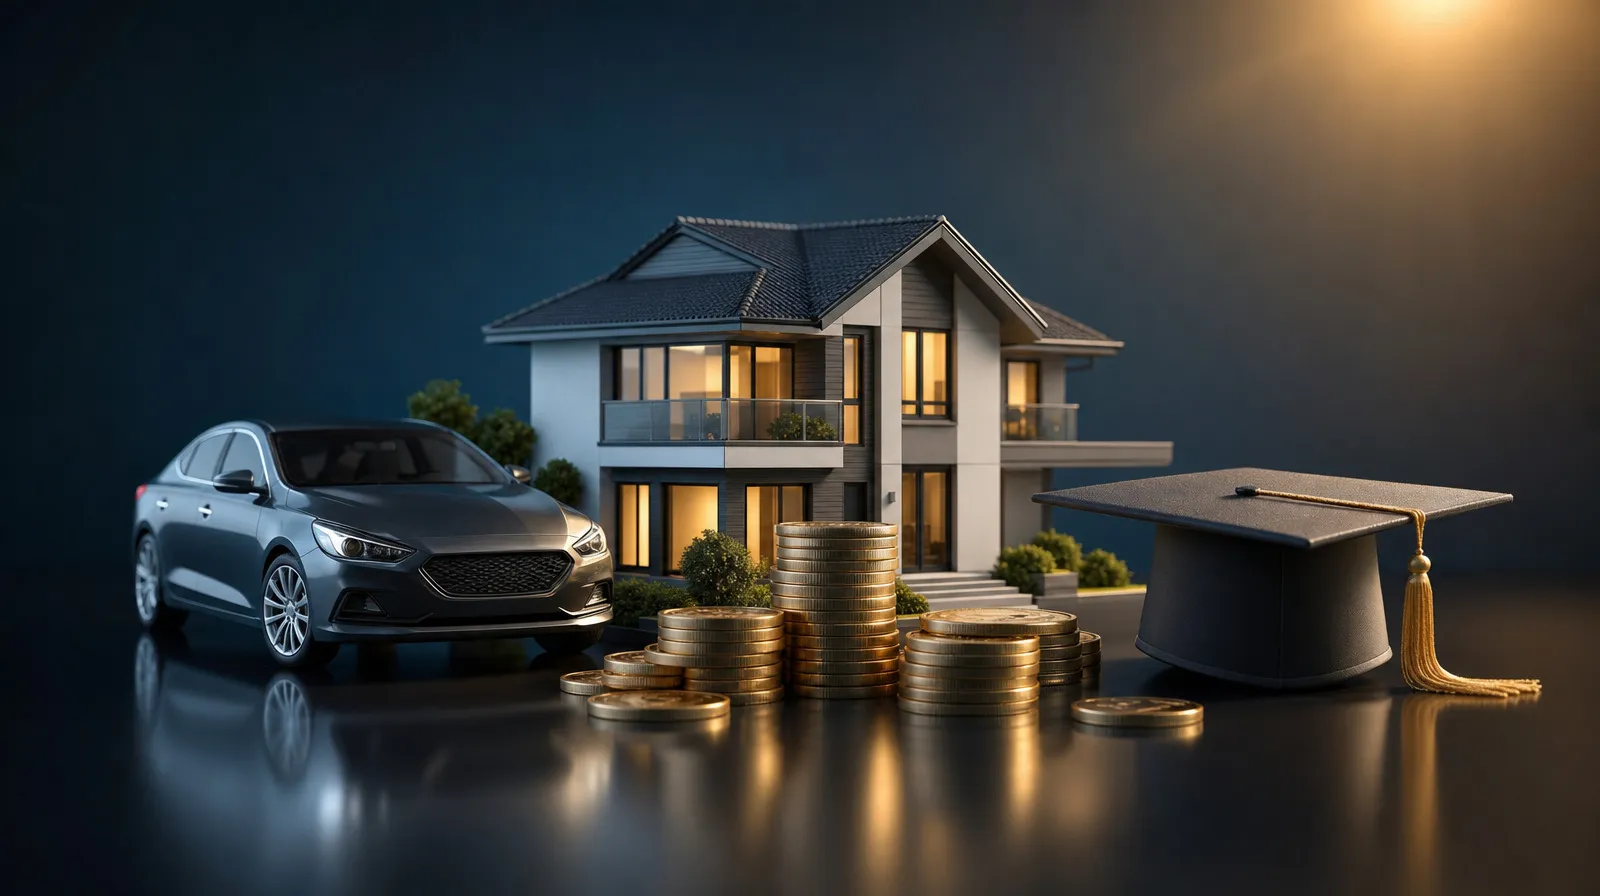
The most common types of loans
Personal loans
A personal loan is an unsecured loan with a fixed amount, a set term, and predictable payments. You don't need to put up your car or home as collateral.
They are the most versatile: you can use them for medical emergencies, home repairs, unexpected expenses, or debt consolidation . According to LendingTree (2026), 53.1% of borrowers use personal loans to consolidate debt or refinance credit cards. The average personal loan debt is $11,768 per person.
Pros:
- No collateral required
- Fixed, predictable monthly payments
- Funds available in days, not weeks
- Some fintechs accept applicants with an ITIN
If you are facing an unexpected expense, a personal loan from a responsible lender can be the most direct way to resolve it. Discover where to apply for a personal loanKiwi offers personal loans that you can apply for 100% from your phone, with a soft pull that does not affect your credit score.
Subject to credit approval. Loan amounts may vary depending on the applicant's state of residence.
Mortgage loans
A mortgage is a loan backed by the property you are purchasing. It is likely the largest loan you will ever take out, with terms ranging from 15 to 30 years. Mortgage interest rates can be fixed or variable, and that decision will impact your monthly payment for decades.
There are several types within this category:
- Fixed-rate: your monthly payment remains the same throughout the entire term
- Adjustable-rate (ARM): the rate can go up or down after an initial period
- FHA: backed by the federal government, with lower down payment requirements
- VA: exclusive to veterans and active-duty military personnel
- USDA: for eligible rural areas
If owning a home is a goal, look into FHA programs. Some mortgage lenders accept ITINs, which opens doors that many assume are closed. Availability varies by state and lender, so be sure to ask directly.
Auto loans
An auto loan uses the vehicle as collateral. If you stop making payments, the lender can repossess the car.
Used cars typically have higher rates and shorter terms than new ones. Getting pre-approved by your bank or credit union before heading to the dealership gives you more bargaining power.
What to avoid: "buy here, pay here" lots. These dealerships target people with limited credit history and charge significantly higher rates. They seem like the easiest option, but the total cost of the loan ends up being much higher.
Student loans
Student loans fund university or technical education. There are two main categories:
Federal loans (from the U.S. government):
- Direct Subsidized: the government pays the interest while you are in school
- Direct Unsubsidized: interest accrues from the start
- PLUS loans: for parents or graduate students
Private loans (from banks or online lenders):
- Generally require an SSN and credit history
- Do not offer income-driven repayment plans
- Do not qualify for forgiveness programs
Exhaust all federal options before considering private loans. Federal loans offer protections that private ones do not. Without an SSN or eligible immigration status, your access to federal loans is limited.
Payday loans and other high-risk loans
Payday loans, title loans, and pawn loans share one characteristic: quick access to cash with extremely high costs.
According to the Federal Reserve (2025), 10% of Hispanic adults used some type of payday, pawn, or title loan in 2024. Nationally, 6% of all U.S. adults used these non-bank credit products.
Why they are dangerous:
- According to the CFPB, the annual percentage rates (what is APR) can exceed 300% or 400%
- They are designed to create cycles of renewal and continuous debt
- Title loans put your vehicle at risk
They fill a real gap. When you need $200 today and don't have access to a bank or your credit score is low, a payday lender doesn't ask for extensive documentation. The problem isn't that they exist. It's that they are often the only visible option.
More responsible alternatives: personal loans from regulated lenders, credit unions, and fintechs that evaluate your actual financial behavior. Kiwi offers personal loans as an alternative to these high-cost products, with a 100% digital process and no origination fees.
Subject to credit approval. Loan amounts may vary depending on the applicant's state of residence.
What other articles don't tell you
Tandas are not loans, but they do teach financial discipline. If you participate or have participated in tandas or cundinas, you already understand the commitment of paying on time and community trust. That experience is valuable. The difference: formal loans offer legal protections (state regulation and rate caps) that tandas do not. It's about knowing when each option makes sense.
With an ITIN, you can access more options than you think. Many Latinos assume that without a Social Security Number (SSN) they cannot apply for any loan. The reality is different: among the types of loans that exist, some personal loan lenders, FHA mortgage programs, and credit unions accept the ITIN (Individual Taxpayer Identification Number). The barrier is almost always a lack of information, not a lack of eligibility.
The interest rate is not the only cost. When comparing loans, also check for origination fees, late fees, and prepayment penalties. The loan that seems cheapest is not always the one that costs you the least in the end.
Compare the total cost, not just the monthly payment. A low monthly payment with a long term can cost you significantly more than a higher payment with a short term. Learn how to calculate the interest rate to compare options objectively. Let's look at an example:
Note: This is a fictional example for illustrative purposes. The amounts, APRs, payments, and costs shown do not represent actual offers, rates, or terms from any lender or service provider.
The $108 payment seems more comfortable. But you end up paying $324 more. Always ask for the total cost of the loan before signing.
Watch out for the fine print in Spanish. Some lenders offer advertising in Spanish but contracts only in English. You have the right to understand what you are signing. If the contract is not available in Spanish, ask for a detailed explanation of each term before agreeing.
Apply for up to $3,000
Frequently asked questions
How many types of loans are there?
There are more than 8 common types: personal, mortgage, auto, student, payday, title, pawn, and lines of credit. Each has its own subtypes. The right one for you depends on what you need the money for and your current financial situation.
What are the types of bank loans?
The different types of bank loans include personal, mortgage, auto, student loans, and lines of credit. Credit unions offer similar products, often with better terms for their members. Fintech companies expand access beyond traditional banking, especially for people with limited credit history.
Can I apply for a loan without a Social Security number?
Yes. Some lenders accept an ITIN (Individual Taxpayer Identification Number) for personal loans, FHA mortgages, and credit union loans. Check the requirements for personal loans for more details. Availability varies by lender and state. Kiwi accepts applicants with an ITIN in select markets.
Subject to credit approval. Loan amounts may vary based on the applicant's state of residence.
What type of loan is best for an emergency?
Personal loans from responsible lenders are usually the best option. Avoid payday loans. Consider the amount you need, the term, and the total cost. For small emergencies ($150 to $3,000), a short-term personal loan can resolve the situation without creating a debt cycle.
What is a fixed vs. variable interest rate?
A fixed rate means your monthly payment does not change for the life of the loan. A variable rate can go up or down based on market conditions. A fixed rate is more predictable; a variable rate may start lower but carries risk. For short-term personal loans, a fixed rate is almost always the safer choice.
Is a bank loan or a fintech loan better?
It depends on your situation. Banks have established infrastructure but stricter requirements. Fintechs offer faster approval, more flexible criteria (such as ITIN acceptance), and a digital experience right from your phone. Learn about the advantages of online loans.
How can I avoid predatory loans?
Red flags include: "no credit check" advertising, pressure to sign immediately, hidden fees, and an APR above 36% (the threshold that the Military Lending Act as a protection limit). Ask for the total cost in writing. Verify that the lender is licensed in your state. The Consumer Financial Protection Bureau (CFPB) publishes free guides on your rights at consumerfinance.gov. If it seems too easy, it probably has a catch.
Key points
- Knowing the types of loans helps you make smarter financial decisions.
- Personal loans are the most flexible option for handling emergencies.
- Avoid payday loans: their real cost is much higher than it seems.
- With an ITIN, you can access personal loans, mortgages, and more. Get informed first.
- Always compare the rate, term, fees, and total cost before signing.